LinkTown Residences Review: Is It Worth Buying? Pros, Cons & Who It Suits
An honest pre-launch review of LinkTown Residences (Hougang Central Residences): what the integrated location gets right, the trade-offs, pricing risk against Hougang resale and past integrated launches, and who it suits.
LinkTown Residences (Hougang Central Residences) has not opened its showflat yet, but there is already enough public information to judge the fundamentals. This is our honest pre-launch review: what the Hougang Central condo gets right, where the risks are, and who should, and shouldn’t, be looking closely. We will update it once official prices and the site plan are released.
Quick facts first
- Mixed-use GLS site at Hougang Central, District 19, 99-year lease.
- About 830 homes, developed by a joint venture of CapitaLand Development (50%), UOL (40%) and Kheng Leong (10%).
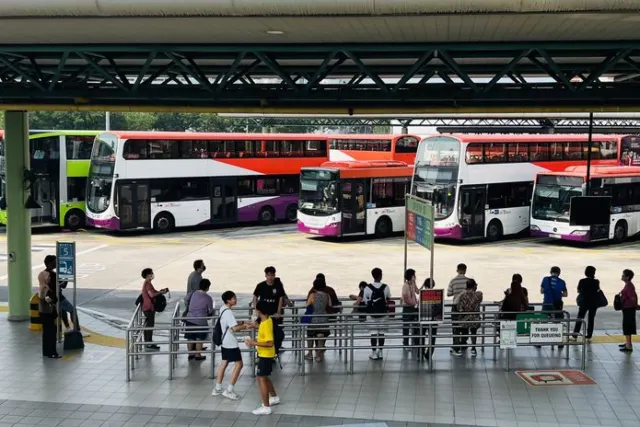
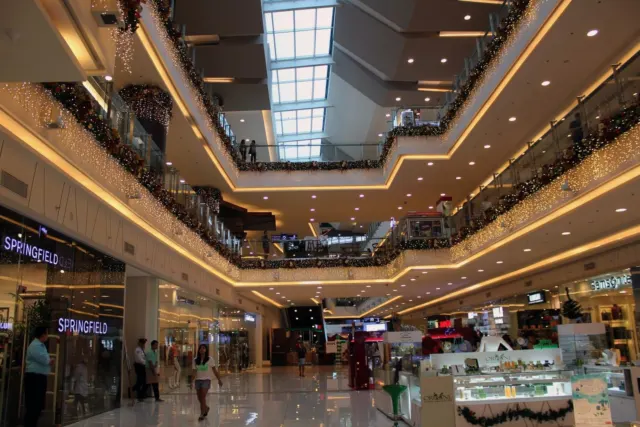
- A mall of about 300,000 sq ft NLA, 100% owned by CICT, plus a new bus interchange and town plaza.
- Directly linked to Hougang MRT (NE14), a future North-East Line and Cross Island Line interchange.
- Sales launch expected early 2027; completion expected around 2030 to 2031.
For the background on the land deal, see how CapitaLand and UOL won the Hougang Central site.
The case for buying
- The location is the product. Few homes in Singapore sit directly on an MRT interchange with a mall and a bus interchange downstairs. Once the Cross Island Line opens (Phase 1 targeted around 2030), Hougang becomes one of the better-connected stations in the north-east.
- Scarcity. This is the first major mixed-use GLS site in Hougang in over a decade. Integrated sites in mature estates don’t come up often.
- An under-served retail market. Hougang has around 230,000 residents but only about 2.8 sq ft of private retail space per person, against a national average of about 11.4 sq ft. A mall set to be the largest in Hougang fills a real gap.
- A single mall owner. CICT will own and run the mall as one asset, which usually means more consistent upkeep and tenant mix than strata-titled retail.
- Developers with an integrated track record. UOL and CapitaLand Development were part of the Parktown Residence joint venture, and CapitaLand was behind Sengkang Grand Residences. Both were integrated projects of a similar type.
- A natural upgrade for Hougang HDB owners. Many buyers will be upgrading from HDB within the town they already know, which tends to support demand.
The trade-offs
- Price. At an expected S$2,500 to S$2,600 psf, it will sit well above existing Hougang condos. You pay for the integration up front.
- Busy surroundings. Stacks facing the plaza, bus interchange or mall frontage will be livelier than a typical condo. Stack choice will matter.
- Size. With about 830 units, facilities are shared by many households, and on resale there will usually be other units competing with yours.
- Long wait. Completion is expected around 2030 to 2031. Your money is committed for several years before you can move in or rent it out.
- Unknowns. Facilities, unit mix, maintenance fees and the exact layout are not yet announced.
Pricing risk: how does it compare?
This is the part that decides whether it is “worth it”. Here is how the analyst estimate stacks up against nearby and comparable projects, based on reported transaction data (approximate figures).
| Project | Type | Approx. psf |
|---|---|---|
| LinkTown Residences (estimate) | New launch, integrated | S$2,500–2,600 (expected, not official) |
| Parktown Residence, Tampines | New launch, integrated | ~S$2,360 at launch weekend (Feb 2025); ~S$2,484 later |
| Sengkang Grand Residences | Completed ~2023, integrated | ~S$2,011 resale average in 2025 |
| The Florence Residences, Hougang | Resale, non-integrated | ~S$1,877 (12 months to mid-2026) |
| Riverfront Residences, Hougang | Resale, non-integrated | ~S$1,736 (12 months to mid-2026) |
What this tells us:
- Against Hougang resale, the estimate is roughly 33% to 50% higher per square foot. Part of that gap is new versus older stock, part is the integration premium.
- Against Parktown Residence, the estimate is close to Parktown’s later reported average of about S$2,484 psf. Buyers will be comparing a Hougang interchange location with Parktown’s Tampines North setting.
- Against Sengkang Grand Residences, the completed integrated project in the region resold at about S$2,011 psf in 2025, so an S$2,500 psf entry is about 24% higher. That is the gap future buyers of LinkTown Residences would need to see narrow or be justified by the MRT interchange.
We compare these in more depth in LinkTown Residences vs Parktown Residence and LinkTown Residences vs nearby Hougang condos.
Resale and exit: thinking beyond launch day
Most buyers focus on the entry price, but the exit matters just as much. When LinkTown Residences completes, around 830 owners will share one address, and some will want to sell or rent at the same time. Your unit will compete with identical layouts in the same development, so the things that set a unit apart, such as a quieter stack, a better view or a practical layout, become more valuable.
The integration helps here. Sengkang Grand Residences, the closest completed integrated example in the region, averaged about S$2,011 psf on resale in 2025, above the non-integrated Hougang resale condos in the table, based on reported transaction data. That suggests the market does pay for direct MRT and mall access over time. But a higher entry price leaves less room for gains, so a sensible plan is to buy a unit you would be happy to hold for many years, not one that only works on a quick flip.
Who it suits
| Buyer | Fit | Why |
|---|---|---|
| Hougang/Sengkang HDB upgraders | Strong | Stay in a familiar town with a big step up in convenience |
| Young families | Strong | Montfort Junior School next to the site, sheltered access to MRT and mall |
| Own-stay buyers who commute by MRT | Strong | NEL now, CRL interchange targeted around 2030 |
| Investors (rental) | Good | Doorstep MRT and mall support demand; entry price is the key risk |
| Buyers who need a home soon | Weak | Completion only expected around 2030 to 2031 |
| Buyers wanting peace and quiet | Weaker | A town-centre address will never be as quiet as a residential enclave |
What to wait for before committing
- The official price list. Compare actual psf by unit type, not the average. Smaller units usually carry a higher psf.
- The site plan. Where the towers sit relative to the bus interchange, the plaza and the MRT link changes which stacks are desirable. Check our site plan page for updates.
- Floor plans. The indicative sizes we use are based on the developers’ Parktown Residence, not official. See floor plans.
- Your own finances. Get an in-principle approval and check stamp duty before launch day.
Our verdict
LinkTown Residences looks set to be one of the stronger north-east launches of 2027 on location alone. The question isn’t whether it’s a good development. It’s whether the launch price leaves enough room.
For own-stay families and Hougang upgraders who value the MRT interchange and mall, the premium is easier to justify, because you are buying daily convenience for many years. For investors, the case depends on entry price and stack. If launch prices land at the lower end of estimates, it looks competitive against Parktown Residence. If they land well above, the gap to Hougang resale and Sengkang Grand becomes harder to justify on numbers alone.
Set your budget with our calculators, read the price estimate by unit type, and register your interest to receive the official price list as soon as it is released.
This review is independent and for general information only. It is not financial advice. Prices are analyst estimates; comparable figures are approximate and based on reported transaction data. The project name has not yet been officially confirmed.
If you are also looking at nearby towns, see our comparisons of Punggol, Sengkang and Serangoon and Kovan condos, and the LinkTown Residences FAQ.