Hougang BTO vs Buying a Condo at Hougang Central: Which Path Fits Your Family?
Waiting for a Hougang BTO or buying a condo at Hougang Central? We compare cost, eligibility, waiting time, MOP rules, financing and flexibility, so you can pick the path that fits.
For many young families in the north-east, the choice looks like this: apply for a Hougang BTO and wait, or stretch for a private condo at Hougang Central. Both can work. They just suit different budgets, timelines and plans. This guide compares the two paths conceptually, so you can see where your family fits before you look at any price list.
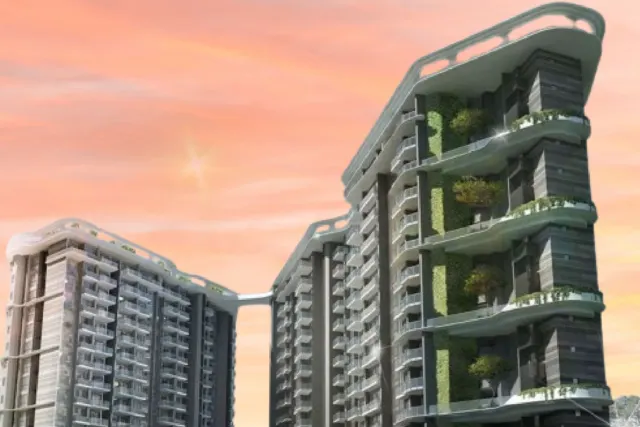
We use LinkTown Residences (Hougang Central Residences), the integrated development planned above Hougang MRT, as the condo example. Its prices are not yet announced, so condo figures below are analyst estimates only.
Is there a Hougang BTO coming?
HDB now runs Build-To-Order sales in regular exercises. In 2026 it planned about 19,600 BTO flats across three exercises, in February, June and October. HDB’s preview of the October 2026 exercise covered projects in towns such as Bedok, Geylang, Sembawang, Tengah, Toa Payoh and Yishun, and did not include a Hougang BTO project.
Hougang is a mature town with limited vacant land, so BTO launches here are less frequent than in newer towns. If you are set on living in Hougang, check the HDB Flat Portal for each upcoming BTO launch, and consider resale flats or nearby towns as alternatives. We don’t list specific future sites here, because HDB only confirms them close to each exercise.
BTO vs condo at a glance
| Hougang BTO (new HDB flat) | Condo at Hougang Central | |
|---|---|---|
| Who can buy | Eligible citizens meeting HDB rules on citizenship, family nucleus, income ceiling and property ownership | Anyone may buy a non-landed condo; ABSD depends on residency and number of properties |
| Price level | Subsidised; housing grants for eligible first-timers | Market price; analysts expect ~S$2,500–2,600 psf for LinkTown (not official) |
| Wait | Several years for most projects; some shorter-wait projects | New launch: pay progressively and wait for completion (LinkTown expected 2030/2031); resale condo: move in now |
| Minimum occupation | 5 years (Standard flats) or 10 years (Plus and Prime flats) | No MOP |
| Renting out | Whole-flat rental restricted until MOP; rules apply after | Allowed (minimum 3 consecutive months for private homes) |
| Loans | HDB loan or bank loan; MSR 30% applies | Bank loan only; TDSR 55% applies, no MSR |
| Facilities | Town and estate amenities | Condo facilities; at LinkTown, a mall and bus interchange below |
General comparison only; check eligibility and rules with HDB, IRAS and your bank. Rental rules for private homes are per URA’s minimum rental period.
Cost: the biggest difference
BTO flats are priced below market and eligible first-timers can receive grants, which is why the BTO route is the default for most young couples. Resale gives a sense of market value: Hougang HDB resale medians in January–September 2026 were about S$619,000 for a 4-room flat and S$775,000 for a 5-room flat. New BTO prices are set separately by HDB for each project. Our HDB vs condo in Hougang comparison looks at costs, space and lease in more depth.
A condo costs much more. On analyst estimates of S$2,500–2,600 psf, a 2-bedroom of about 678 sq ft at Hougang Central could be roughly S$1.70m–1.76m, and a 3-bedroom of about 1,066 sq ft roughly S$2.67m–2.77m. These sizes come from the developers’ recent Parktown Residence and are not LinkTown’s confirmed plans. Add stamp duty: BSD on S$1.7m is about S$54,600. See our stamp duty guide.
Eligibility and ownership rules
- BTO buyers must meet HDB’s eligibility conditions, including income ceilings and property ownership rules. Households generally must not own private residential property, and anyone who owned one must have disposed of it at least 30 months before applying for the HDB Flat Eligibility (HFE) letter.
- HDB owners buying a condo must first meet the MOP of their flat. After the MOP, Singapore Citizens can buy a condo and keep the flat, but ABSD for a second property applies (20% for citizens), unless they sell the flat and qualify under IRAS’s rules.
- Executive condominiums are a middle route with their own rules, including a S$16,000 household income ceiling and a 5-year MOP. LinkTown Residences is a private condo, not an EC; see our EC explainer.
Standard, Plus and Prime: why the flat type matters
Since October 2024, new HDB flats are classified as Standard, Plus or Prime instead of mature and non-mature estates. Standard flats have a 5-year MOP. Plus and Prime flats, in more central or well-connected locations, have a 10-year MOP and a subsidy recovery when sold. For a family planning to upgrade to a condo, this is critical: a 10-year MOP pushes the earliest upgrade date back by five years compared with a Standard flat. Check the classification of any upcoming BTO launch before you apply.
Financing: MSR vs TDSR
HDB flat buyers face the mortgage servicing ratio (MSR), which caps property loan instalments at 30% of gross income, as well as TDSR if they borrow from a bank. Private condo buyers face only TDSR at 55%. In practice, a household can often borrow considerably more for a condo than for a flat on the same income, though the condo also costs more. Our MSR vs TDSR guide has worked examples.
Three common paths for Hougang families
1. BTO now, condo later
Buy a BTO (or resale flat), live there through the MOP, build equity and CPF savings, then sell and upgrade. This is the classic route. It keeps costs low in the early years, but depends on the MOP length and future prices. Our HDB upgrader guide covers the sell-and-buy sequence.
2. Upgrade from an existing flat
If you already own an HDB flat past its MOP, a new launch lets you pay progressively while you still live in your flat. Timing the sale matters because of ABSD and cash flow. Our new launch vs resale guide for upgraders compares the options.
3. Go straight to a condo
Some buyers, for example those above the income ceiling or who want flexibility to rent or sell, skip HDB entirely. You give up subsidies and grants, and need more cash upfront, but face no MOP or HDB occupation rules.
Which path fits your family?
- Tight budget, eligible, flexible on timing: BTO or resale HDB.
- HDB owner past MOP, growing family: consider upgrading to a condo, new or resale.
- Above income ceilings or want freedom to rent out: a private condo.
- Want Hougang specifically: watch each BTO exercise, but keep resale and condo options open, since Hougang BTO supply is limited.
If a condo at Hougang Central is on your list, register your interest in LinkTown Residences to get prices, floor plans and preview dates when they are announced.
General information only. HDB eligibility, grants, MOP and flat classifications, and IRAS stamp duty rules change from time to time; verify with HDB, IRAS, CPF and your bank. Information as at Sep 2026.