HDB vs Condo in Hougang: Costs, Space, Lease and Lifestyle Compared
HDB vs condo in Hougang, side by side: purchase price, loans and monthly costs, space, the 99-year lease, lifestyle and what it takes to upgrade from an HDB flat to a condo like LinkTown Residences.
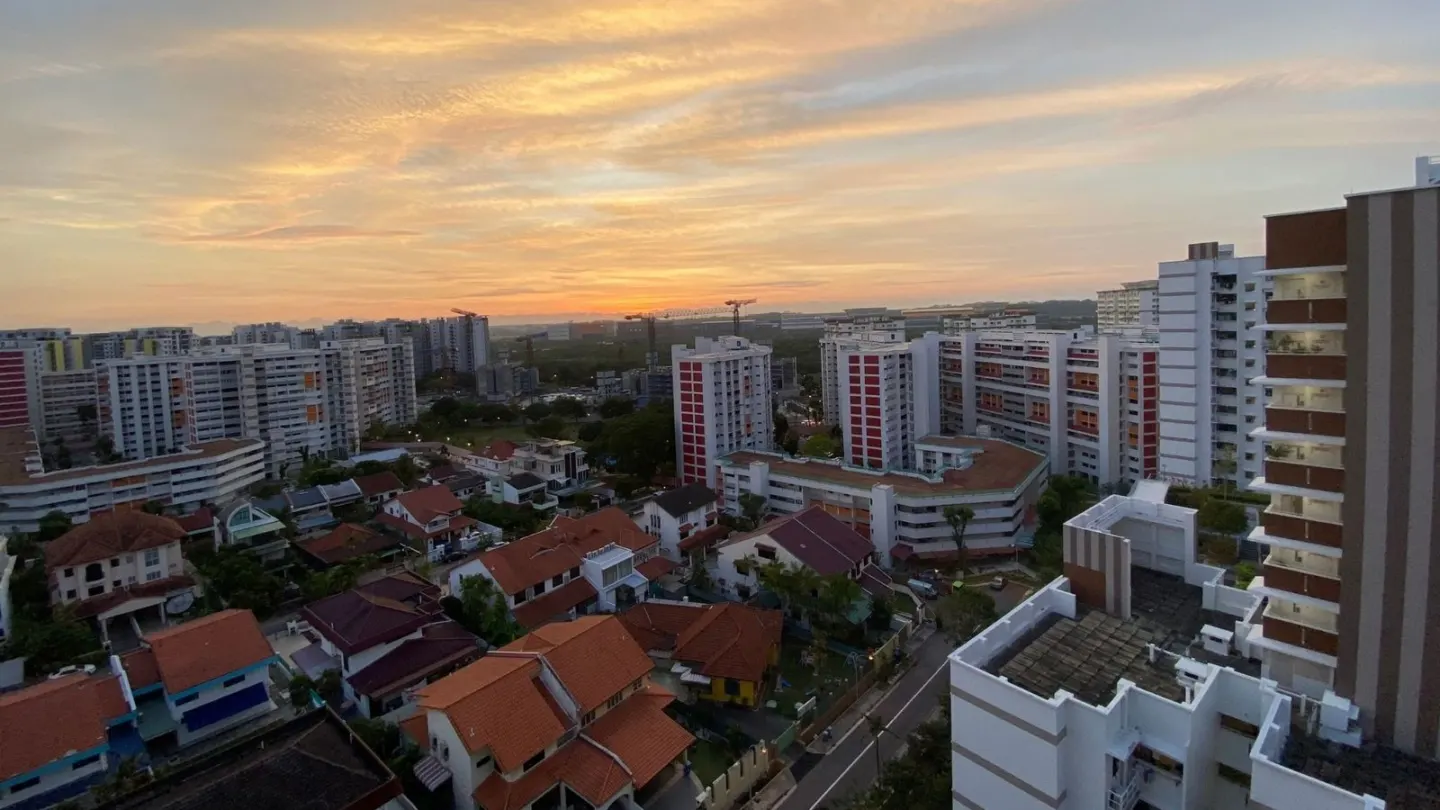
HDB vs condo is the biggest housing decision many Hougang families face. Hougang is a mature estate with established schools, hawker centres and parks, and plenty of well-kept HDB flats. Now a large new condo is coming to its centre: LinkTown Residences (Hougang Central Residences), the integrated development above Hougang MRT. For many owners, the question has become real: stay in an HDB flat, or upgrade to a condo in the same town?
This guide compares the two on cost, space, lease and lifestyle, using Hougang HDB resale medians and illustrative LinkTown Residences figures. It avoids appreciation claims; nobody can promise how either will perform.
HDB vs condo: the price gap in Hougang
| Price (approx.) | Basis | |
|---|---|---|
| Hougang 4-room HDB resale | ~S$619,000 | Median, Jan–Sep 2026 |
| Hougang 5-room HDB resale | ~S$775,000 | Median, Jan–Sep 2026 |
| LinkTown 2BR Premium (~678 sq ft) | ~S$1.70m–1.76m | Illustrative at S$2,500–2,600 psf |
| LinkTown 3BR Premium (~1,066 sq ft) | ~S$2.67m–2.77m | Illustrative at S$2,500–2,600 psf |
LinkTown Residences figures use analysts’ expected psf and indicative sizes from the developers’ Parktown Residence; they are not official prices. HDB medians are approximate.
For an upgrader, the most useful comparison is often a 5-room flat against a 2- or 3-bedroom condo. Selling a 5-room flat near the median might cover a good part of the 25% down payment on a 2-bedroom, after repaying any outstanding loan and refunding CPF with accrued interest. Our HDB upgrader guide works through that example step by step.
Loans and eligibility
- HDB flat: can be financed with an HDB loan (if eligible) or a bank loan. The Mortgage Servicing Ratio (MSR) and TDSR apply.
- Private condo: bank loan only, no HDB loan. TDSR (55% of gross income) applies, tested at a 4% interest rate. MSR does not apply to private condos.
- Down payment: for a condo with a first bank loan, 25% of the price, of which at least 5% in cash. See our guide to the condo down payment.
At a 4% stress-test rate over 30 years, a 75% loan on a S$1.7m unit (S$1.275m) works out to about S$6,087 a month, which needs a combined gross income of about S$11,100 a month with no other debts. That is the practical line many Hougang households need to clear. Our guide to how much condo you can afford lets you test your own numbers.
Monthly and running costs
Beyond the loan, the ongoing costs differ in size and type:
| Cost | HDB flat | Condo |
|---|---|---|
| Estate fees | Service & conservancy charges to the town council | Maintenance fees to the MCST (management + sinking fund), set by share value |
| Property tax | Owner-occupier rates on a lower Annual Value | Owner-occupier rates on a higher Annual Value |
| Insurance | HDB fire insurance plus optional home contents cover | Home contents cover; building insurance arranged by the MCST |
| Interest during construction | Not applicable for resale | For a new launch, interest on progressive drawdowns |
We don’t quote maintenance fees for LinkTown Residences; they haven’t been set. Our guide to the cost of owning a condo lays out every item.
Space: what you get for the money
Hougang has many older flats, and older 4- and 5-room flats are often generous in size. A 5-room flat is typically around 110 sqm (about 1,180 sq ft) of floor area, while a 3-bedroom condo of about 1,066 sq ft sounds comparable on paper.
The difference is how condo space is counted. Condo strata area can include air-con ledges, balconies, planter or bay-window areas and the household shelter. So usable space in a 3-bedroom condo is often noticeably less than a 5-room flat. On the other hand, the condo adds shared space: pools, gyms, function rooms and landscaped decks. Our guide on reading a condo floor plan explains what to check.
99-year lease: condo vs HDB
Both HDB flats and LinkTown Residences sit on 99-year leases. The key difference is where you start on the lease:
- Many Hougang resale flats were built decades ago, so their remaining lease is shorter. That can limit CPF usage and loan tenure for future buyers of the flat.
- A new launch condo starts with a nearly full lease. By the time LinkTown completes around 2030/2031, the lease will have a few years used, but still far more remaining than most resale flats.
Leases decline in value as they run down, whether HDB or condo. Our leasehold vs freehold guide covers lease decay in more depth.
HDB vs condo appreciation: what we can and can’t say
You will see many claims that condos “appreciate more” than HDB flats, or the reverse. Outcomes depend on the specific project, entry price, timing, holding period and market cycle. We don’t make appreciation claims without a source for the specific comparison.
What you can do is look at the data yourself: URA’s private residential price index, HDB’s resale price index, and actual transaction prices for the projects and flats you are comparing. Also factor in the costs: stamp duty, interest, maintenance and, if you sell a private home within four years of purchase, Seller’s Stamp Duty as announced for purchases from 4 July 2025.
Lifestyle: staying in a condo vs HDB
- Facilities: condos have pools, gyms and function rooms. HDB estates rely on public facilities, and Hougang has many: Hougang Sports Centre, Hougang Swimming Complex, Punggol Park and community clubs.
- Security and privacy: condos have guarded access and fewer neighbours per lift lobby. HDB living is more open and communal.
- Convenience: an integrated condo like LinkTown adds MRT, bus interchange and a large mall downstairs. Many Hougang flats are also near town-centre amenities, but not directly linked.
- Community: HDB neighbourhoods have strong estate life. Condo communities vary; large developments can feel like a town of their own.
HDB upgrade to condo: the rules to know
- MOP first. You can’t buy private property until your flat has met its Minimum Occupation Period, usually five years (longer for some newer flat types). Check your flat’s MOP date on HDB’s portal.
- ABSD if you keep the flat. A Singapore Citizen buying a second home pays 20% ABSD. Married couples can get a refund if they sell the first home within the IRAS time limit (for an uncompleted purchase, generally six months after TOP or CSC, whichever is earlier). See our stamp duty guide.
- New launch or resale? A new launch gives time to sell your flat before completion; a resale condo means moving sooner. Our comparison of new launch vs resale for HDB upgraders covers both routes.
- EC or private condo? ECs have income ceilings and resale restrictions. LinkTown Residences is a private condo, not an EC; see is LinkTown Residences an EC?
So, HDB or condo?
Stay in your HDB flat if your priority is low monthly costs, you like your block and neighbours, and you would stretch too far to upgrade. Consider a condo if your household income comfortably clears the TDSR test, your flat has built up equity, and you value facilities, a new lease and, in LinkTown’s case, an MRT interchange at your door.
If you are a Hougang HDB owner weighing the move, register your interest and we’ll share LinkTown Residences prices when they are released, so you can compare real numbers rather than estimates.
General information only, as at Sep 2026. HDB medians and LinkTown figures are approximate and illustrative. Verify rules with HDB, IRAS, CPF and your bank.