CapitaLand–UOL Win Hougang Central with S$1.5b Bid: What It Means for Buyers
The S$1,179 psf ppr Hougang Central GLS bid, explained: who bid what, how close the bids were, who builds what, and what the land price signals for future home prices.
On 16 December 2025, the Hougang Central tender for the mixed-use Hougang Central GLS site (Government Land Sales) closed with three bids. The winner was a consortium of UOL Group, CapitaLand Development (CLD) and CapitaLand Integrated Commercial Trust (CICT), with a top bid of S$1.5 billion, or S$1,179 psf per plot ratio (ppr). The site was formally awarded on 14 January 2026. The homes on it are being marketed as LinkTown Residences (Hougang Central Residences).
This guide unpacks the Hougang Central GLS tender for home buyers. It covers who bid, what the numbers mean, who is building what, and what a land price can and cannot tell you about the eventual launch price.
Hougang Central GLS: the bids at a glance
| Rank | Bidder | Total bid | psf ppr |
|---|---|---|---|
| 1 | UOL, CapitaLand Development & CICT | S$1.50b | S$1,179 |
| 2 | Sim Lian Group | S$1.47b | S$1,155 |
| 3 | Frasers Property, Sekisui House & Lum Chang | ~S$1.40b | ~S$1,100 |
Key dates: the tender closed on 16 December 2025 and the award was made on 14 January 2026. The site is 99-year leasehold, in District 19. It is the first major mixed-use GLS site in Hougang in more than a decade.
What “psf ppr” actually means
Land bids in Singapore are compared using psf ppr, or dollars per square foot per plot ratio. It is simply the total land price divided by the maximum gross floor area (GFA) allowed on the site.
- The Hougang Central site is about 504,820 sq ft of land.
- Its plot ratio is 2.5, so the allowable GFA is roughly 504,820 × 2.5 ≈ 1.27 million sq ft.
- S$1.5 billion ÷ ~1.27 million sq ft works out to about S$1,179 psf ppr.
Why not quote the land price per square foot of land? Because what a developer can sell depends on how much floor space it can build, not how big the plot is. Psf ppr puts sites of different sizes and densities on the same footing. It is the number to compare against other land bids, and the starting point for any launch-price estimate.
One caveat. This site includes about 430,556 sq ft of commercial space as well as homes, so the S$1,179 psf ppr is a blended figure across both. How the consortium splits the land cost internally between the residential and commercial parts has not been published.
Reading the bid spread
The winning bid was only 2.06% above Sim Lian’s second-placed bid, a gap of roughly S$30 million on a S$1.5 billion site. The third bid, at about S$1,100 psf ppr, was roughly 7% below the winner.
How to read that:
- A tight top-two gap usually means experienced bidders valued the site in a similar way. The winner did not have to pay far above what others were prepared to pay. That lowers the risk that the land price forces launch prices well above what the market will bear.
- Three bids is a moderate turnout. It is a large, complex, capital-heavy site, and only groups able to fund both a big condo and a large mall could realistically take it on. That limits the field.
- Different bidder types. Two of the three bidders were consortiums pairing residential developers with commercial or construction partners. That tells you the mall and transport components were central to how the site was valued.
What is being built
- About 830 homes (some sources say up to ~835), developed by a residential joint venture of CLD (50%), UOL (40%) and Kheng Leong (10%), per UOL’s August 2026 results presentation, and sold as private condominium units. Total GFA is about 1.27 million sq ft.
- A mall of about 300,000 sq ft of net lettable area, developed and 100% owned by CICT at a development cost of about S$1.1 billion. It is set to be the largest mall in Hougang.
- A new Hougang bus interchange, integrated into the development.
- A town plaza with sheltered public event space, and a range of F&B.
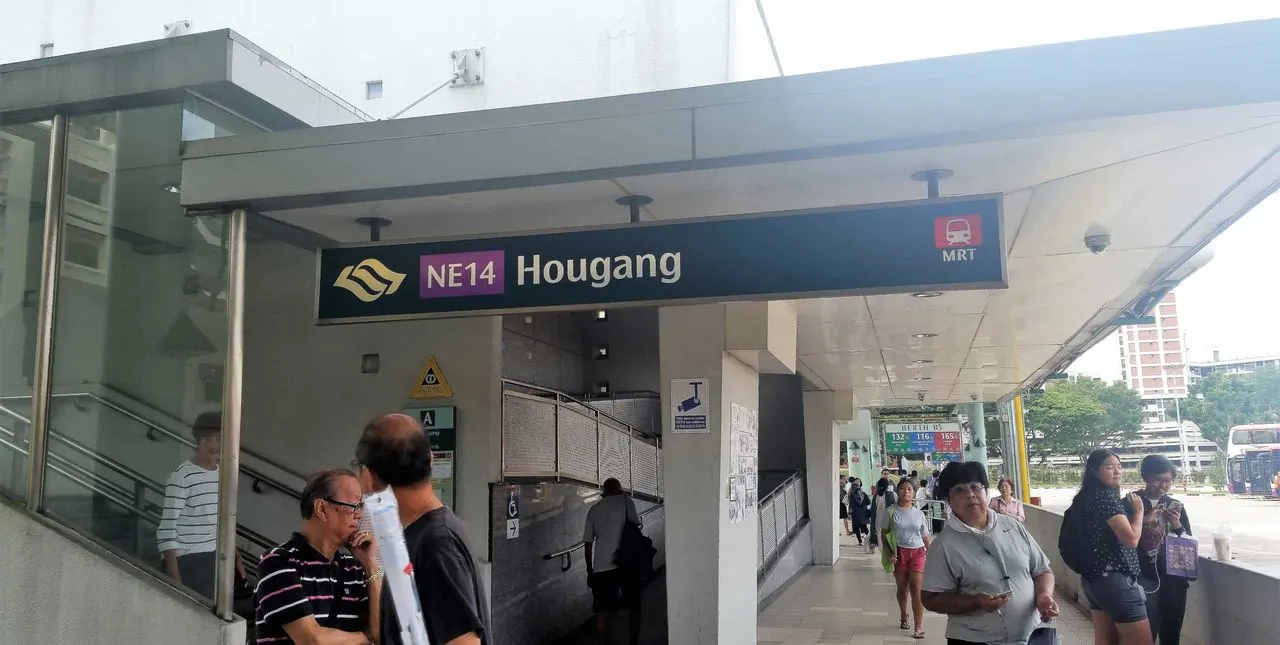
- A direct link to Hougang MRT (NE14) on the North-East Line, which is set to become a Cross Island Line interchange around 2030.
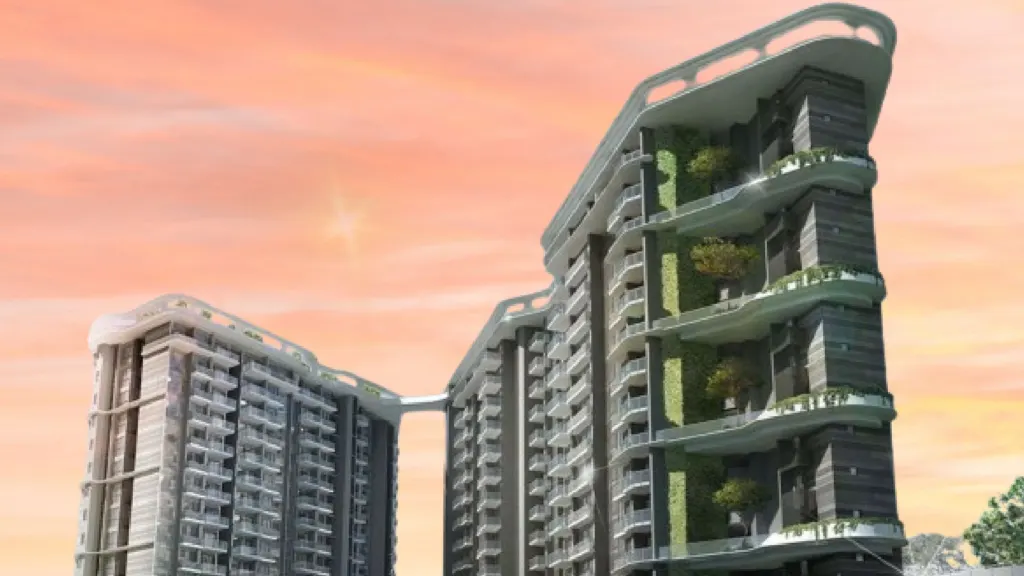
Expected completion is around 2030/2031, with the residential sales launch expected in early 2027 (UOL’s August 2026 results guide a 2H 2027 launch). The site plan page tracks what is known about the layout.
Who does what: the partners’ roles
- 40%UOL GroupA long-established listed group with residential projects and hotels (Pan Pacific, PARKROYAL). Recent projects include Parktown Residence and Amo Residence. Co-develops the homes.
- 50%CapitaLand DevelopmentThe development arm of CapitaLand Group, behind projects such as One Pearl Bank. Co-develops the homes with UOL and Kheng Leong.
- 10%Kheng LeongA Singapore property developer and minority partner in the residential joint venture, per UOL’s August 2026 results presentation. It was not named in the land award. Co-develops the homes.
- 100%CICTCapitaLand Integrated Commercial Trust, owner of malls including Plaza Singapura, Tampines Mall, Junction 8 and Bugis Junction. Develops and owns the mall.
Note the two different groupings. The bidding consortium named in the award was UOL, CLD and CICT. The residential joint venture that develops and sells the homes is CLD (50%), UOL (40%) and Kheng Leong (10%); CICT owns 100% of the commercial component.
This split matters to buyers. The homes are sold by the residential joint venture. The mall is held long term by a REIT whose business is running malls, which gives it a strong reason to keep the tenant mix and upkeep in good shape. More on the groups is on our developer page.
It is also a familiar team. UOL and CLD partnered on Parktown Residence in Tampines, another integrated project with a mall, bus interchange and future CRL station. That project’s sales record is the closest comparison available (see below).
What the land price signals for home prices
A land bid is a cost, not a price tag. Developers add construction, financing, fees, taxes, marketing and a margin before arriving at a selling price. Based on the S$1,179 psf ppr land rate, analysts expect an average launch price of around S$2,500 to S$2,600 psf. There are no official prices yet.
Some useful reference points, based on reported transaction data (approximate):
- Parktown Residence sold about 87% of its 1,193 units on its February 2025 launch weekend at an average of about S$2,360 psf, and was later reported about 98% sold at an average of about S$2,484 psf.
- Existing Hougang resale condos such as Riverfront Residences (about S$1,736 psf) and The Florence Residences (about S$1,877 psf) transacted well below the expected LinkTown range over the past 12 months.
So the land price points to a new-launch level well above Hougang resale and broadly in line with the Parktown outcome. Our price estimate guide walks through the land-to-launch maths, and the price page shows illustrative quantums by unit type.
Why Hougang, why now
Hougang has about 230,000 residents, but only about 2.8 sq ft of private retail space per person, against a national average of about 11.4 sq ft. That undersupply is a big part of why a ~300,000 sq ft mall made sense to the bidders. Residents today often travel to other towns for larger malls.
For the homes above it, that matters in two ways. First, daily convenience: groceries, dining and services sit downstairs. Second, demand: a large catchment of HDB households in the estate is a natural pool of upgraders who may want to stay near family, schools and the NEL. Our HDB upgrader guide looks at that route in detail.
The bottom line
The Hougang Central GLS was won by a well-resourced consortium at a price close to what a rival was willing to pay. The land rate implies a launch level around S$2,500–2,600 psf, in the same bracket as the team’s Parktown Residence. For buyers, the questions to prepare for now are budget, financing and which unit type suits you, rather than trying to guess the exact launch price.
If you would like the official price list and floor plans as soon as they are released, register your interest below.
Figures are as reported at the time of the tender and award, and are approximate. Price expectations are analyst estimates, not official prices.